Budapest is not breaking ranks with Brussels. It is reading the shipping manifests.
Read the standard coverage of Hungary pushing for a renewed US sanctions waiver on Russian energy exports—following the one-year exemption granted after Viktor Orbán met Donald Trump in November 2025, ahead of its November 2026 expiration, and alongside US Treasury moves opening channels for Russian diesel—and you get the same tired script. Brussels versus Budapest. Moral solidarity versus Kremlin appeasement. A landlocked country holding the EU hostage for cheap fuel.
That script is lazy. Worse, it gets the mechanics backward.
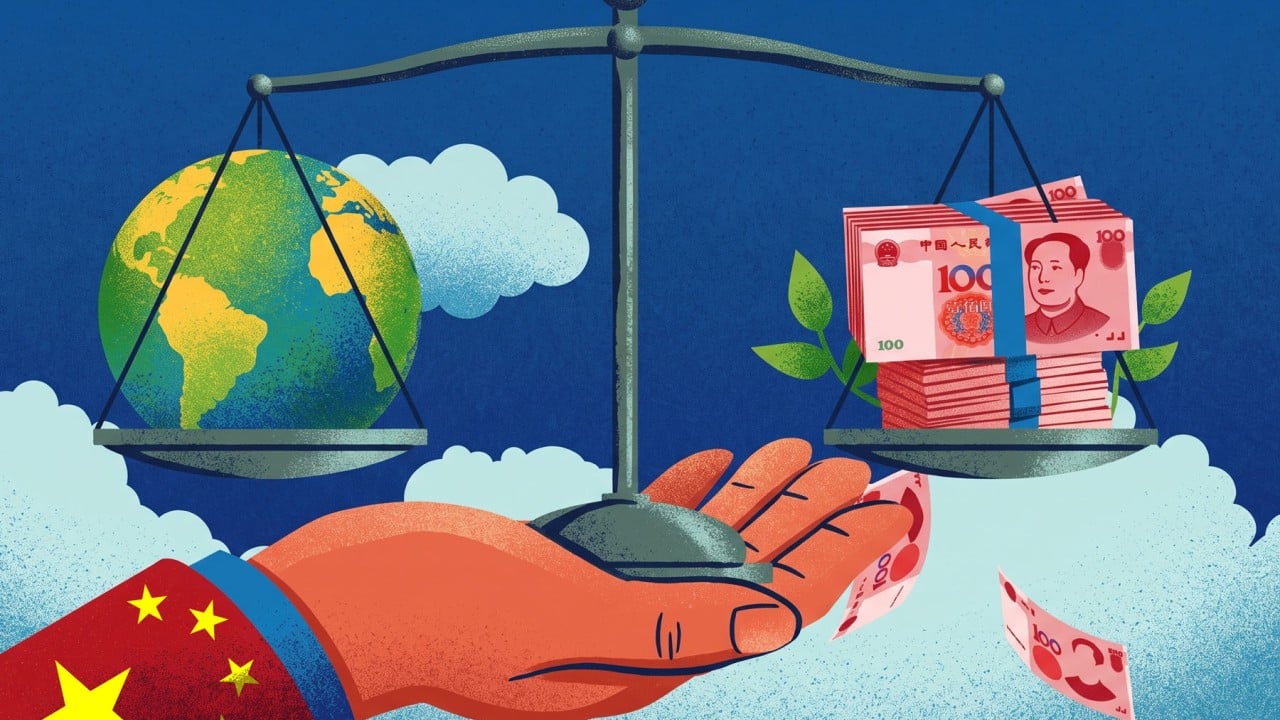
The real story is not that Hungary is secretly bankrolling Moscow while the rest of Europe rides a high horse of pure, non-Russian energy. The real story is that European fuel markets run on fungible molecules, maritime workarounds, and refinery economics that make "sanctions compliance" look a lot like accounting theater. When Washington issues temporary general licences or grants one-year exemptions and Budapest scrambles to extend them, nobody is inventing a new heresy. They are fighting over who pays the transport and compliance tax on a global diesel market that still clears through Russian barrels.
The Wrong Question Everyone Keeps Asking
Most commentary asks: How can Hungary get away with defying the EU on Russian diesel and oil?
Wrong question. Ask instead: Why did Brussels build a sanctions architecture that punishes visible pipeline flows while leaving seaborne product laundering, tanker juggling, and LNG loopholes wide open?
Critics love to point at Hungary—and fellow pushback voices like Slovakia's Robert Fico or Bulgaria's Radev—as the rogue variables spoiling European unity. Meanwhile, data from analysts like the Centre for Research on Energy and Clean Air (CREA) show that EU member states continued paying Russia billions in fossil fuel imports well into 2026, with Russian LNG still flowing into European terminals ahead of the EU's 2027 ban and seaborne oil products moving on vessels tied to G7+ maritime services.
When an EU state buys pipeline crude under a carved-out exemption, the invoice is visible, the pipe is fixed, and the political outrage is easy. When middle-distillates get blended, re-exported through third hubs, or transferred ship-to-ship, the moral ledger stays clean on paper while the physical balance sheet tells a very different story.
If you treat Hungary's waiver push as a pure ideological betrayal rather than a predictable scramble by a landlocked refiner protecting margins and supply optionality, you miss where the leverage actually sits. Washington uses waivers and licences as geopolitical poker chips—tying exemptions to commitments like US liquefied natural gas purchases or broader diplomatic bargaining. Budapest knows that game cold.
Why "Landlocked Helplessness" Is Half-Truth and Half-Excise
Let's be precise about the terms before we go any further. Crude oil is unrefined petroleum pulled from the ground; diesel (a middle distillate) is a refined fuel produced in a refinery through atmospheric and vacuum distillation followed by hydrotreating to strip sulfur. Conflating crude exemptions with diesel trade flows is where half the bad commentary starts.
Landlocked geography is real. Hungary does not have a deepwater coastline, which means it cannot simply pull a tanker up to a domestic jetty the way Rotterdam or Gdansk can. When the Druzhba pipeline faces disruptions—such as the early 2026 drone strike on the Kaleykino pumping station that hit flows toward Central and Eastern Europe—the physical plumbing gets tested fast.
I have watched commodity desks and industrial buyers blow millions hedging the wrong bottleneck—betting on headline diplomatic bans instead of refinery configuration and pipeline throughput. You can pass all the decrees you want in Brussels or Washington, but a refinery designed around specific crude slates, or a landlocked system constrained by transit tariffs and pumping capacity on routes like the Adria (JANAF) pipeline, cannot flip a switch overnight without eating higher costs or margin compression.
At the same time, Hungarian officials have not lived in a vacuum of pure victimhood. Strategic reserves—mandated at 90-day equivalents under EU rules—have been drawn down for domestic price interventions and then rebuilt through stock rotations and crude-to-product shifts. Saying "we have no choice" is great politics in Budapest; pretending there are zero commercial trade-offs or alternative routing options is bad analysis.
Imagine a scenario where Washington lets a Russian diesel licence or Hungarian sanctions exemption lapse cold on a Tuesday with zero substitute supply lined up. Within weeks, regional transport and agricultural diesel costs spike, industrial input prices pass straight through to consumer goods, and domestic political pressure forces either an emergency price cap (draining strategic stocks all over again) or a frantic backchannel carve-out. That is why pragmatic governments—even ones that talk tough on transition timelines—keep a foot in the waiver door.
"People Also Ask" — Dismantled
Does Hungary's push for a US-Russia diesel deal prove the EU's energy sanctions have failed?
No—because "failed" assumes sanctions were ever a binary on/off switch rather than a friction mechanism. Sanctions and price caps have squeezed Russia's export revenues compared to unconstrained sales, forced reliance on shadow tankers, and raised transaction costs. Calling them a total failure ignores revenue compression; calling them airtight ignores ship-to-ship transfers, re-export hubs, and G7+ shipping involvement. Neither extreme survives contact with the data.
Why would the US grant or allow Russian diesel flexibility while backing Ukraine?
Because Washington's playbook has always mixed pressure with market-stabilization valves. When global fuel balances tighten or inflation threatens to bite consumers, policymakers reach for licences, waivers, and bilateral leverage—demanding things like LNG purchase commitments or negotiating posture in return. Moral consistency is a press-release standard; supply-chain math is a Treasury standard.
Can Hungary realistically quit Russian energy fast?
Not without paying a steep fiscal and industrial bill—and even longer transition targets like 2035 leave plenty of wiggle room. S&P has noted that alternative gas sources like Azerbaijan and Qatar can help diversify supply, while flagging vulnerability in Hungary's fiscal and external accounts if an energy shock hits. Speed without affordability is political suicide for any government in Budapest.
Where My Contrarian Take Can Burn You
Here is the honest downside of viewing this through cold commercial realism rather than Brussels orthodoxy: it can lull you into underestimating political and security tail risks.
Pipelines are physical targets, not spreadsheets. Sanctions regimes shift abruptly when Washington changes tack or enforcement tightens on insurers, tankers, and blending hubs. If you assume a waiver will always be renewed or a discount will always exist, you can get caught long on exposure right when a transit line goes offline or a compliance crackdown hits. Realism is not cynicism; it is pricing tail risk properly.
What to Do Instead of Arguing Headlines
If you run an energy-exposed business, trade commodities, or manage macro risk in Europe, stop trading the Hungary vs. EU soap opera and do three concrete things instead:
- Track origin laundering, not just direct bilateral imports. Watch re-export hubs, blending terminals, and maritime insurance/vessel data—because molecules move around legal labels faster than regulators update rules.
- Stress-test against choke points, not press releases. Model a two-to-six-week pipeline interruption alongside tight middle-distillate cracks and reserve drawdowns.
- Price policy whiplash into every contract. Treat sanctions waivers and general licences as temporary instruments with expiration dates, not permanent market fixtures.
Let the pundits argue over who is the bigger villain in Brussels. The market only cares whose tanks are full when the winter barrels get tight.