Picture a fluorescent-lit kitchen at six o'clock on a rain-slicked Tuesday morning. A kettle clicks off. A toddler cries down the hall. On the laminate counter sits a stack of envelopes—one for the electric company, one for the mortgage servicer, one from a dentist whose bill looked larger than expected. Nobody in that kitchen uses the word macroeconomics. Yet every calculation made in the glass towers of central banks and university economics departments eventually lands on that laminate counter, wearing the disguise of a grocery receipt, a mortgage rate, or a sudden layoff notice.
For decades, the tools used to map how an entire economy breathes, stumbles, and recovers had a troubling habit of missing the human pulse. When prices climbed or factories slowed, older models often treated people like tidy averages—like marbles rolling down a smooth chute. Real life is messier. People freeze when headlines turn dark. Families delay buying a car or signing a lease not because a textbook told them to, but because a neighbor lost a shift or a health bill arrived out of nowhere. Meanwhile, you can find related developments here: Structural Asymmetry in the Global Automotive Market and the Paris Motor Show Realignment.
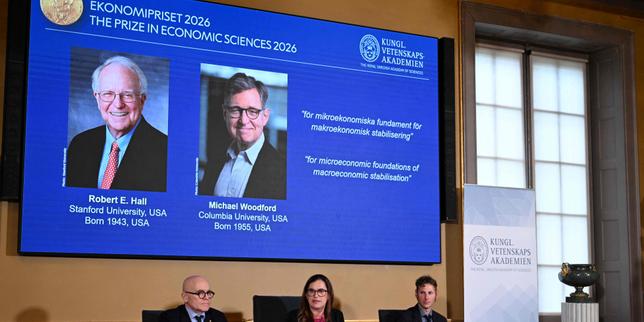
That tension—between cold, neat equations and the lived, jittery reality of households and businesses—sits at the heart of the work associated with American economists Robert Hall and Michael Woodford, whose contributions to macroeconomic analysis helped reshape how policymakers and scholars think about economic fluctuations, interest rates, and expectations. Let's be clear about the ground we're standing on: this article is written in English, inspired by a French-language headline honoring Robert Hall and Michael Woodford for rebuilding the framework of macroeconomic analysis, without access to the underlying competitor article itself. Where I use stories or comparisons to make abstract ideas tangible, I will mark them plainly so the facts and the fiction never blur.
Why Old Maps Left Travelers Stranded
To understand why rebuilding a macroeconomic framework matters, imagine trying to navigate a mountain range with a map drawn from satellite photos taken ten years ago. The peaks are roughly where they used to be. The valleys still sit between them. Yet a landslide has blocked a pass, a new river cuts across an old trail, and fog settles every afternoon. To see the full picture, check out the detailed report by The Wall Street Journal.
That comparison is a metaphor, not a literal description of economic data. Still, it captures a real frustration that economists faced when studying business cycles—those recurring waves of expansion and contraction that shape jobs, wages, and savings. If your model assumes markets clear effortlessly every single day, or assumes everyone reacts to news in the exact same mechanical way, you can be blindsided when recovery drags or when inflation proves stubborn.
Consider a hypothetical scenario. Suppose a mid-sized bakery in Ohio decides whether to buy a second commercial oven. The owner isn't just staring at today's interest rate on a screen. She is wondering whether local families will keep buying birthday cakes next winter, whether flour suppliers will hike prices again, and whether her best baker will stay if hours are cut. Her choice ripples outward: to the equipment maker, to the local electrician, to the part-time delivery driver paying off a used car.
Traditional macroeconomics sometimes struggled to hold all of those moving pieces together in one coherent picture. Fluctuations aren't just random shocks hitting from outside like hailstones on a tin roof. They are shaped by how people look ahead, how quickly or slowly prices and wages adjust, and how credit and spending feed back into one another.
The Weight of Expectations and the Reach of Policy
When central bankers adjust interest rates, people often talk about it as if a dial were being turned and the economy immediately obeyed. Reality is far more human. And far more slippery.
Think about what happens when a central bank signals that it intends to keep interest rates higher for a while to cool inflation. Even before a single loan renews, households and firms start adjusting their plans. A couple looking at houses might pause. A logistics company might hold off on expanding its fleet. Expectations act like a current beneath the surface of the water: you cannot always see it from the dock, yet it pulls boats off course long before they hit the open sea.
Microeconomic choices—the quiet, daily decisions of workers, shoppers, and managers—accumulate into macroeconomic tides. When economists bridge that gap more carefully, asking not just what happened yesterday, but how people form expectations about tomorrow and how frictions slow adjustment, the entire analytical map becomes sharper.
I have sat across kitchen tables—and in cramped community rooms—listening to people try to make sense of economic shifts that experts debate in calm, measured tones. To a family watching rent climb while overtime dries up, an "output gap" or a "monetary policy rule" sounds like Latin chanted from a distance. It feels distant. Sometimes it feels alienating. I won't pretend these subjects are simple or cozy; macroeconomics can be intimidating, full of jargon that makes ordinary people wonder if they missed a class everyone else attended.
Admitting that confusion is part of being honest. You don't need a PhD to care about whether your paycheck stretches through the end of the month, and you shouldn't need a decoder ring to understand why economic frameworks evolve.
What Rebuilding a Framework Actually Means
When headlines say economists have reconstructed or rebuilt a macroeconomic framework, what are they really talking about? They aren't pouring concrete or laying bricks. They are revising the set of assumptions, equations, and logical links used to test "what if" questions before real people pay the price for a wrong guess.
A simple analogy helps here. Think of a weather forecaster upgrading from a single barometer on the porch to a network of sensors tracking wind shear, humidity, and ocean currents. That is an analogy, not a literal claim that economics is meteorology. Economies involve human choices and bargaining, not just air pressure. Yet the spirit of the upgrade is similar: better structure lets analysts see interactions they used to miss.
In modern macroeconomic thinking, several threads keep pulling researchers back toward reality:
- Forward-looking behavior: People don't just react to today's price tag; they weigh what they expect prices, jobs, and interest rates to look like months down the road.
- Rigidities and friction: Contracts aren't renegotiated every hour, wages don't snap up and down like a yo-yo, and switching suppliers or jobs takes time and money.
- Policy constraints: Decisions about interest rates and government budgets interact with public trust and credibility, shaping how strongly policy moves real activity.
None of these ideas turns economics into a crystal ball. Anyone who promises exact predictions about complex human economies is selling moonbeams. Better frameworks don't eliminate uncertainty. They help decision-makers weigh risks more clearly when uncertainty is high.
Two Lives Touched by the Same Tide
To see why these analytical shifts matter beyond academic journals, let's follow two fictional characters—clearly labeled as hypothetical—living through the same economic chill.
First is David, a fifty-four-year-old machinist in Pennsylvania. His shop makes precision parts for industrial gear. When borrowing costs rise and customers delay capital upgrades, orders slow down. David isn't reading central bank transcripts over coffee. He notices the shop floor feels quieter on Thursdays. He feels the knot in his stomach when his supervisor mentions trimming discretionary spending. His confidence is fragile, shaped by a lifetime of knowing that when heavy industry sneezes, small towns catch a cold.
Three hundred miles away is Priya, a twenty-nine-year-old physical therapist renting a studio apartment in Virginia. She has student loans, a modest savings buffer, and a dream of opening a neighborhood clinic one day. When prices for groceries, insurance, and utilities stay elevated, every line item in her budget fights for space. Even if her clinic stays busy, higher rates make starting a business heavier—equipment loans cost more, commercial leases look steeper, and every month of delay carries a cost.
David and Priya never meet. Their jobs look nothing alike. Yet both sit inside the same web of prices, credit, wages, and expectations that macroeconomic frameworks try to represent. When models capture how cautious households become, how firms respond to shifting demand, and how policy ripples through credit markets, they come closer to seeing David's Thursday shift and Priya's clinic notebook as parts of one connected story.
The Quiet Danger of Fighting the Last War
History has a wry sense of humor when it comes to economic ideas. Models built to explain one era often struggle when the next era brings a different twist.
During periods of low inflation and steady growth, policymakers can grow accustomed to a certain rhythm. Then a supply shock hits, or pandemic disruptions scramble global chains, or energy and housing costs surge all at once. Suddenly, rules of thumb that felt reliable start creaking. Debates flare over how fast to raise rates, how long to hold them, and how much slack or strain exists in the labor market.
During moments like that, people often ask: Why can't the experts just agree?
Part of the answer is that real-world data arrives with lag and noise. Employment numbers get revised. Prices move unevenly across sectors—eggs might jump while electronics dip. Another part of the answer is that reasonable economists can look at the same framework and weigh risks differently. One analyst worries more about inflation becoming entrenched; another worries more about tightening so hard that solid businesses go under and workers lose ground needlessly.
Disagreement isn't always proof of incompetence. Sometimes it is the honest friction of people staring into fog and trying not to steer the bus off the cliff.
From Chalkboards to the Grocery Aisle
Why honor work that reconstructs analytical frameworks at all, when the public cares about tangible outcomes like jobs, take-home pay, and affordable housing?
Because bad maps waste real lives. When an analytical framework misses how expectations work or how financial conditions transmit through the economy, policy can arrive too late, push too hard, or pull too softly. Over years, those missteps compound. A few extra months of high unemployment here. A wave of avoidable business closures there. A generation learning to distrust institutions that seemed out of touch.
Conversely, when research sharpens the tools used to understand business cycles, monetary policy, and economic fluctuations, the payoff is quiet. You rarely see a headline thanking a theoretical model for a smooth soft landing or a steadier job market. You only notice what didn't break as badly as it might have.
Think back to that kitchen at six o'clock on a rainy Tuesday. The kettle clicks off. The envelopes still need to be opened. No economic theory can pay a utility bill or soothe a worried parent at two in the morning. Yet behind the scenes, better ideas about how people plan, borrow, spend, and hope help shape the weather outside that window—making the difference between a storm that leaves a family stranded and one they can weather with their footing intact.
Rain beads on the windowpane.