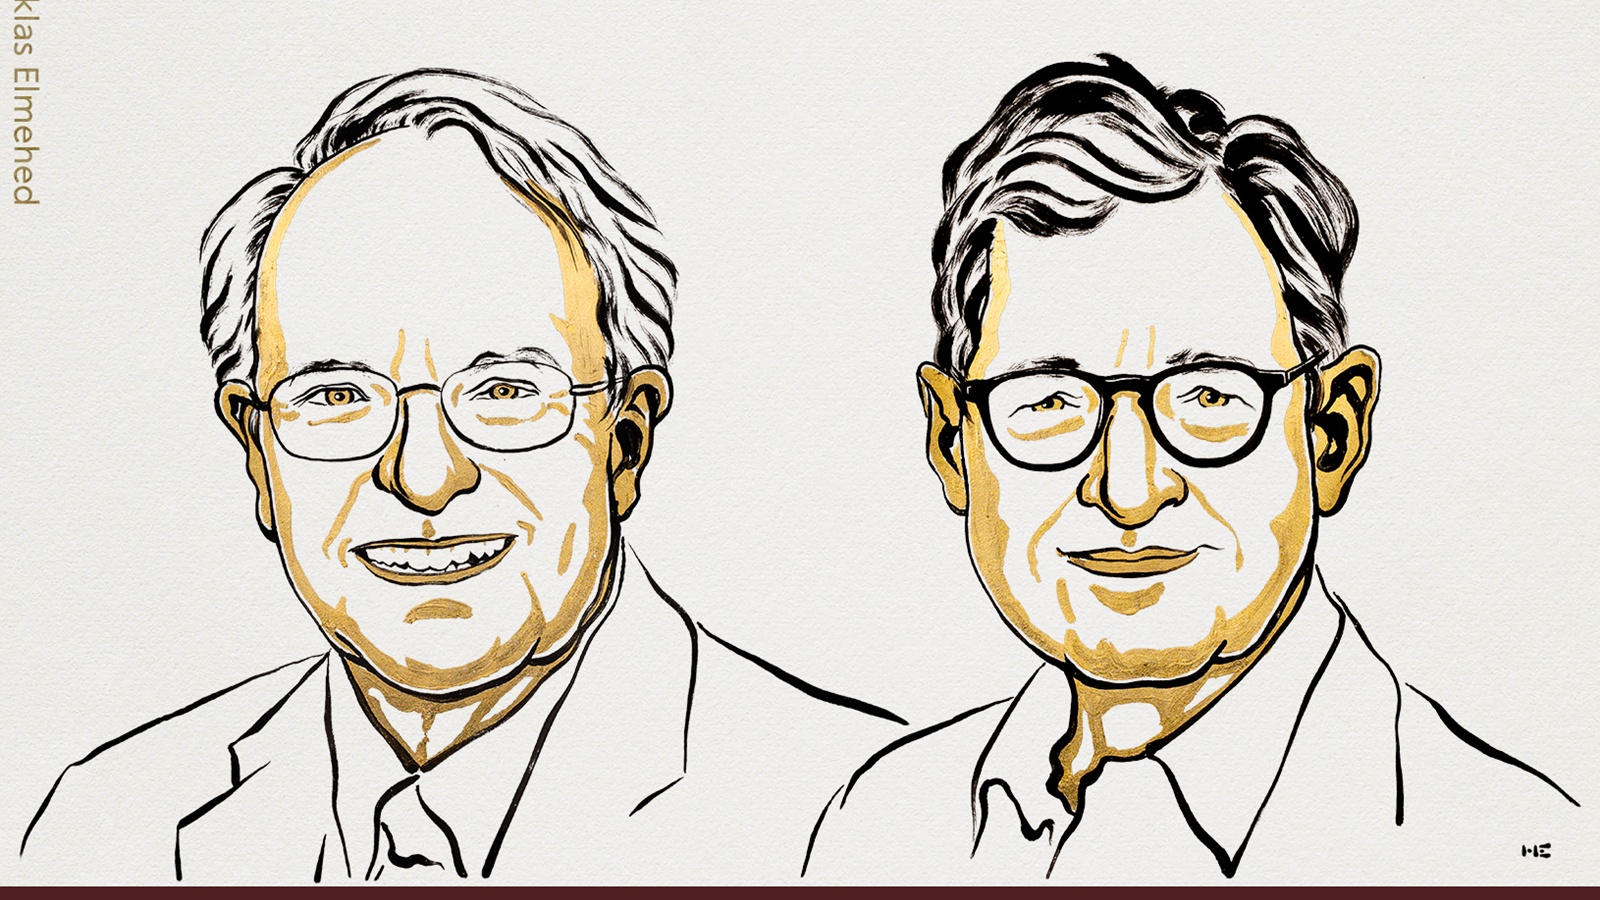
Traditional macroeconomic modeling suffered from a fatal aggregation error. For decades, stabilization policy relied on reduced-form empirical correlations rather than structural decision rules. When structural shocks altered historical behavior, policy parameters failed, culminating in the stagflation crises of the 1970s. The decision by the Royal Swedish Academy of Sciences to award the Sveriges Riksbank Prize in Economic Sciences in Memory of Alfred Nobel 2026 to Robert E. Hall and Michael Woodford marks the formal recognition of the microfoundational counter-revolution. Their work replaced statistical approximations with optimization-based behavioral constraints, transforming monetary and fiscal policy design into a rigorous engineering problem.
The Consumption Puzzle and Rational Expectations
Macroeconomic forecasting stalled on the mechanics of consumer behavior. Early Keynesian formulations assumed aggregate consumption mapped directly to current disposable income via a stable marginal propensity to consume. Yet empirical time series contradicted this assumption, exhibiting excess smoothness and unpredictability that standard formulations could not capture.
Robert E. Hall disrupted this framework in 1978 by introducing the permanent income hypothesis integrated with rational expectations and intertemporal optimization. Hall modeled the consumer as an agent maximizing expected utility over an infinite horizon subject to an intertemporal budget constraint. The mathematical consequence of this optimization is stark: if consumers smooth consumption optimally based on all available information, changes in consumption should follow a martingale difference sequence.
This implies that current consumption depends on lifetime wealth rather than current income, and future changes in consumption are inherently unpredictable using current information. By establishing that predictable components of income changes do not alter consumption paths, Hall systematically dismantled the mechanistic leverage points previously assumed by fiscal policymakers. The structural implication was severe: transitory tax rebates or fiscal transfers designed to boost immediate demand would fail if agents perceived them as temporary deviations from permanent income.
The New Keynesian Synthesis
The Architecture of Stabilization Policy Why the 2026 Nobel Prize Rewrites Macroeconomic Control
news, business
Macroeconomic stabilization has historically oscillated between two intellectual extremes. One camp prioritizes rigid monetary rules designed to anchor expectations over multi-year horizons, while the other advocates for discretionary fine-tuning in response to immediate economic shocks. The 2026 Nobel Prize in Economic Sciences, awarded to Robert E. Hall and Michael Woodford, recognizes a body of work that dissolved this false dichotomy. Their research provides the structural framework necessary to evaluate how monetary policy transmits through complex price networks, labor dynamics, and household balance sheets.
Understanding this contribution requires deconstructing the failure modes of traditional stabilization models. Standard macroeconomic frameworks often treated the price level and aggregate output as aggregates governed by simple mechanical equations. Hall and Woodford replaced this black-box approach by grounding stabilization policy in microeconomic optimization and general equilibrium theory. They demonstrated that the efficacy of central bank interventions depends fundamentally on how private agents form expectations about future policy paths, turning monetary policy into an exercise in signal management rather than mere interest rate adjustment.
The mechanics of their contribution rest upon three distinct analytical pillars: nominal rigidity, expectations-driven asset pricing, and the optimal design of monetary rules under imperfect information.
The Microfoundations of Price Stickiness
Traditional Keynesian models assumed prices were sticky by decree, inserting nominal rigidities into equations without explaining the underlying cost structure of price adjustment. Robert E. Hall challenged this deficit by focusing on the opportunity cost of resource allocation and the friction inherent in labor markets. His work on asset pricing and labor market fluctuations illuminated why employment drops precipitously during recessions while real wages remain relatively stable.
In a frictionless market, wage adjustment would clear excess labor supply instantly. Yet, employment volatility vastly exceeds wage volatility. Hall demonstrated that this phenomenon stems from the implicit relational contracts governing employment relationships and the substantial search frictions that prevent frictionless reallocation. When aggregate demand contracts, firms do not immediately slash wages because the marginal cost of workforce disruption exceeds the short-run savings on the payroll. Instead, they adjust employment quantities.
This realization transforms how stabilization policy must be evaluated. If employment fluctuations are driven by search frictions and labor market rents rather than wage-clearing inefficiencies, monetary policy cannot simply stabilize prices and expect full employment to naturally follow. Central banks must account for the amplification mechanisms embedded within labor supply decisions. Woodford extended this logic into the pricing behavior of intermediate goods producers, showing that even small menu costs generate large macroeconomic consequences when firms operate in monopolistically competitive environments with staggered price adjustments.
The Forward Guidance Breakthrough and Expectations Management
Michael Woodford shifted the center of gravity in monetary economics from current interest rate settings to the trajectory of future policy. His seminal work transformed the New Keynesian framework by proving that private sector behavior today is governed almost entirely by expectations of future policy actions.
The traditional IS curve, which links output to the real interest rate, relies on consumption smoothing. Woodford formalized the New Keynesian IS equation, showing that current consumption depends on expected future real interest rates and expected future income. This introduces a powerful transmission channel: central banks can stimulate aggregate demand during a liquidity trap not by lowering current nominal rates—which are bound at zero—but by committing to maintain low rates long after the economic recovery has begun.
Expected Future Path -> Intertemporal Substitution -> Current Aggregate Demand
This mechanism underpins modern forward guidance. However, Woodford also identified its theoretical vulnerability, known as the forward guidance puzzle. In standard rational expectations models, a promise to keep interest rates low far into the future generates implausibly large economic booms today. Real-world agents exhibit bounded rationality and discounting that dampens this multiplier effect. Recognizing this limitation is vital for policy execution. When central banks issue forward guidance, they must factor in the attenuation caused by consumer myopia and incomplete market participation.
Designing Optimal Monetary Rules
With the conceptual mechanics of expectations and nominal rigidities established, the next challenge lies in operationalizing stabilization policy. Woodford addressed this by deriving normative criteria for central bank behavior, moving away from simple discretion or crude monetary targeting toward robust policy rules.
Under discretion, central banks face a time-consistency problem. They possess an incentive to engineer surprise inflation to boost output in the short run, leading to an inflation bias without any long-run employment gains. To eliminate this bias, policy must be committed to a systematic rule. Woodford evaluated different candidate rules—such as nominal GDP targeting, price-level targeting, and Taylor rules—by constructing a microfounded welfare loss function.
This loss function measures deviations of inflation from its target and output from its efficient level. By second-order approximation of utility functions of representative households, researchers can calculate the exact welfare cost of macroeconomic volatility. Woodford proved that targeting the price level, rather than the inflation rate, can reduce stabilization costs by inducing stabilizing expectations. When inflation undershoots, a price-level targeting regime creates an automatic expectation of future catch-up inflation, lowering real interest rates precisely when monetary stimulus is most required.
Transmission Failures and Balance Sheet Mechanics
Despite the elegance of New Keynesian dynamic stochastic general equilibrium models, real-world stabilization faces severe operational bottlenecks. The theoretical transmission channels assume frictionless financial intermediation and complete asset markets. When banking sectors malfunction, the mapping from policy rates to real economic activity breaks down.
The limitation of interest-rate-centric stabilization becomes evident during credit crunches. When bank balance sheets are impaired, the spread between the policy rate and the borrowing rate faced by households and firms widens unpredictably. Hall’s analysis of asset valuation highlights that investment responds to the shadow value of capital relative to its replacement cost, known as Tobin's q. If financial frictions disrupt asset pricing, monetary policy loses its grip on investment decisions.
Central banks must therefore incorporate balance sheet dynamics directly into stabilization models. Quantitative easing and credit allocation policies are not mere anomalies; they are necessary interventions when the traditional intertemporal substitution channel is blocked by intermediary distress. The integration of financial sector frictions into stabilization theory represents the frontier of the Hall-Woodford paradigm.
Operationalizing Stabilization in High-Inertia Regimes
Translating theoretical optimality into institutional practice requires confronting trade-offs that models often smooth over. Central banks operating under a strict inflation-targeting mandate frequently encounter supply shocks that pit price stability directly against output stabilization.
When a negative supply shock—such as an energy price spike—hits the economy, it generates simultaneous upward pressure on inflation and downward pressure on output. A central bank attempting to stabilize inflation must raise interest rates, deepening the recession. Conversely, accommodating the shock stabilizes employment at the cost of unanchored inflation expectations. Woodford’s loss function provides the calculus for this dilemma, showing that the optimal response depends on the slope of the Phillips curve and the degree of price stickiness. In environments of high price flexibility, the optimal policy requires a more aggressive accommodation of supply shocks to avoid destructive output contractions.
This analytical rigor alters how modern institutions design reaction functions. Policymakers can no longer rely on static heuristics. They must continuously estimate the underlying output gap and the persistence of shocks while accounting for the credibility of their own communication strategy.
The Strategic Play for Modern Monetary Architecture
Central bank credibility is the primary capital asset of modern monetary policy. The frameworks established by Hall and Woodford dictate that institutional design must insulate monetary authorities from short-term political pressures while maximizing transparency regarding reaction functions.
Institutions failing to anchor expectations through systematic, rule-based communication will find their discretionary interventions neutralized by forward-looking markets. Future stabilization efforts must integrate granular microdata on household liquidity constraints and firm-level price-setting behavior rather than relying solely on macro-aggregates. The strategic priority for central banks is to build communication architectures that translate complex reaction functions into clear signals, ensuring that private sector expectations remain aligned with long-term price stability objectives even during severe structural transitions.


