Geoeconomic fragmentation between primary superpowers alters the fundamental routing of global commerce, shifting the vector of industrial dependence rather than eliminating it. When the world's two largest economies disengage from direct trade channels, the systemic shock propagates across secondary markets, creating asymmetric gains and unexpected vulnerabilities for third-party states. Understanding this realignment requires analyzing trade diversion mechanics, supply chain elasticity, and the capital expenditure required to replace deeply integrated manufacturing ecosystems.
Trade diversion occurs when importers substitute goods from the primary trade partners with goods from intermediate nations. This substitution is constrained by capacity limits, technical standards, and geographic friction. When tariffs or non-tariff barriers restrict bilateral exchange between the primary economies, third-party countries frequently absorb the residual demand. However, this absorption capacity depends on whether the intermediary nation possesses excess production capacity or must construct new facilities from a baseline deficit.
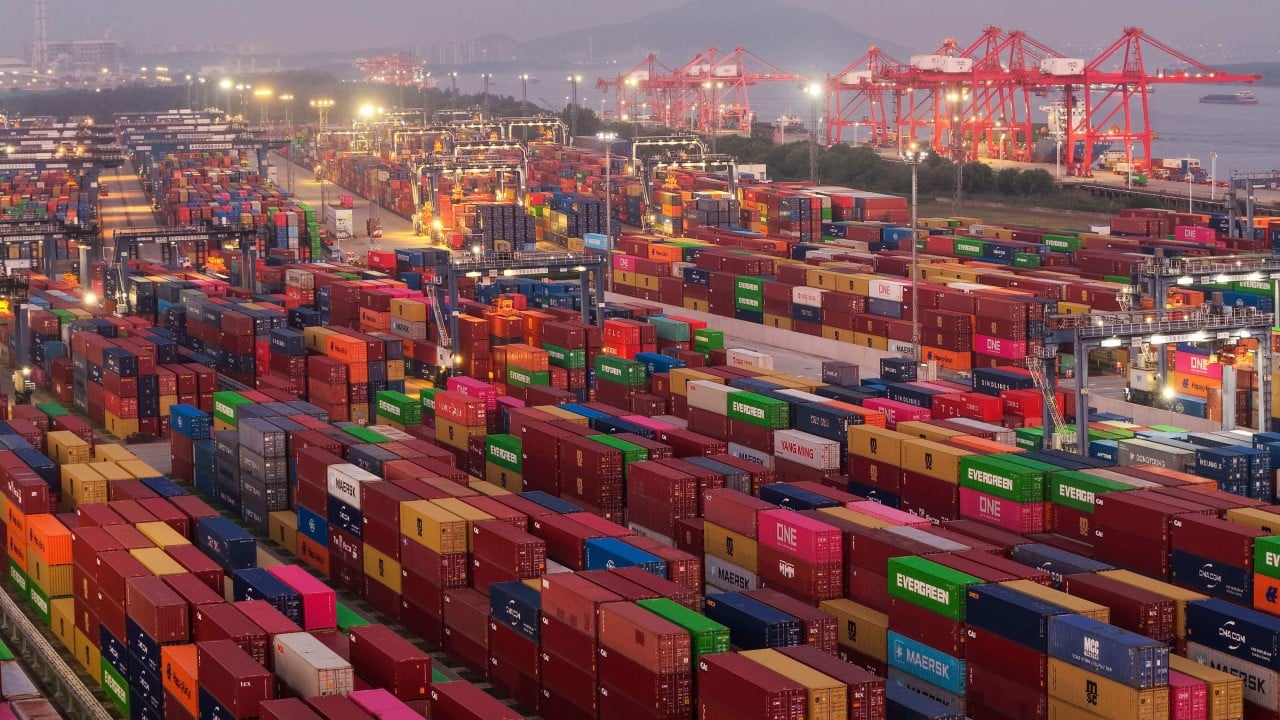
The primary driver of third-party benefit is the arbitrage between direct bilateral trade and indirect routing. Intermediary states often act as transshipment hubs or assembly nodes, importing raw inputs or semi-finished components from the restricted source, processing them marginally, and exporting the finished product to the ultimate destination. This structural position captures economic rent but introduces administrative friction and regulatory scrutiny, particularly as enforcement agencies tighten rules of origin to prevent circumvention.
Industrial capacity cannot be reallocated instantaneously. Capital deployment follows long-term amortization schedules. When nations attempt to substitute established industrial clusters with alternative manufacturing bases, they encounter structural bottlenecks in workforce readiness, logistics infrastructure, and specialized component availability. The marginal cost of production in secondary markets typically exceeds the legacy cost baseline of the original integrated ecosystem. Consequently, any economic gain realized by third-party countries is offset by higher input costs passed down to end consumers.
Bilateral trade data often obscures the distinction between true domestic value addition and mere pass-through trade. Intermediary nations frequently experience a surge in export volumes directed toward the primary consumption markets while simultaneously expanding their import volumes from the restricted producer nation. This dual expansion signals a structural shift in logistics corridors rather than a diversification of underlying industrial provenance. Analysts who measure success solely through export growth metrics misdiagnose transshipment activity as indigenous industrial maturation.
Geographic proximity and existing trade pacts dictate which secondary nations capture the highest share of diverted trade. Proximity reduces transportation overhead and lead times, mitigating the friction of supply chain reconfiguration. Regional trade agreements provide predictable tariff structures that lower the risk barrier for multinational corporations relocating capital assets. Nations lacking these structural advantages remain peripheral to the primary corridors of trade redirection, regardless of their labor cost advantages.
The long-term equilibrium of economic decoupling depends on capital expenditure trends in domestic manufacturing within the consuming economies. If corporations view fragmentation as a temporary political cycle, they will rely on lightweight inventory buffers and marginal geographic adjustments. If they assess the fragmentation as structural and permanent, capital will flow toward heavy industrial reshoring or deep integration with trusted regional allies. This capital allocation decision determines whether third-party beneficiaries experience a permanent industrial expansion or a transient economic windfall.
Resource allocation models must account for the vulnerability of extended supply chains. As routing becomes more circuitous, the number of potential points of failure increases. Redundancy adds cost, creating a permanent tax on global productivity. The strategic imperative for corporate leadership shifts from cost minimization to operational resilience, altering the performance metrics by which global supply chains are evaluated.
Strategic execution in this environment requires continuous monitoring of regulatory compliance thresholds and rules of origin enforcement. Corporations must decouple their forecasting models from historical baseline correlations, recognizing that current structural shifts invalidate past cyclical patterns. Supply chain architecture must be treated as a dynamic asset requiring active risk mitigation rather than a static procurement function.