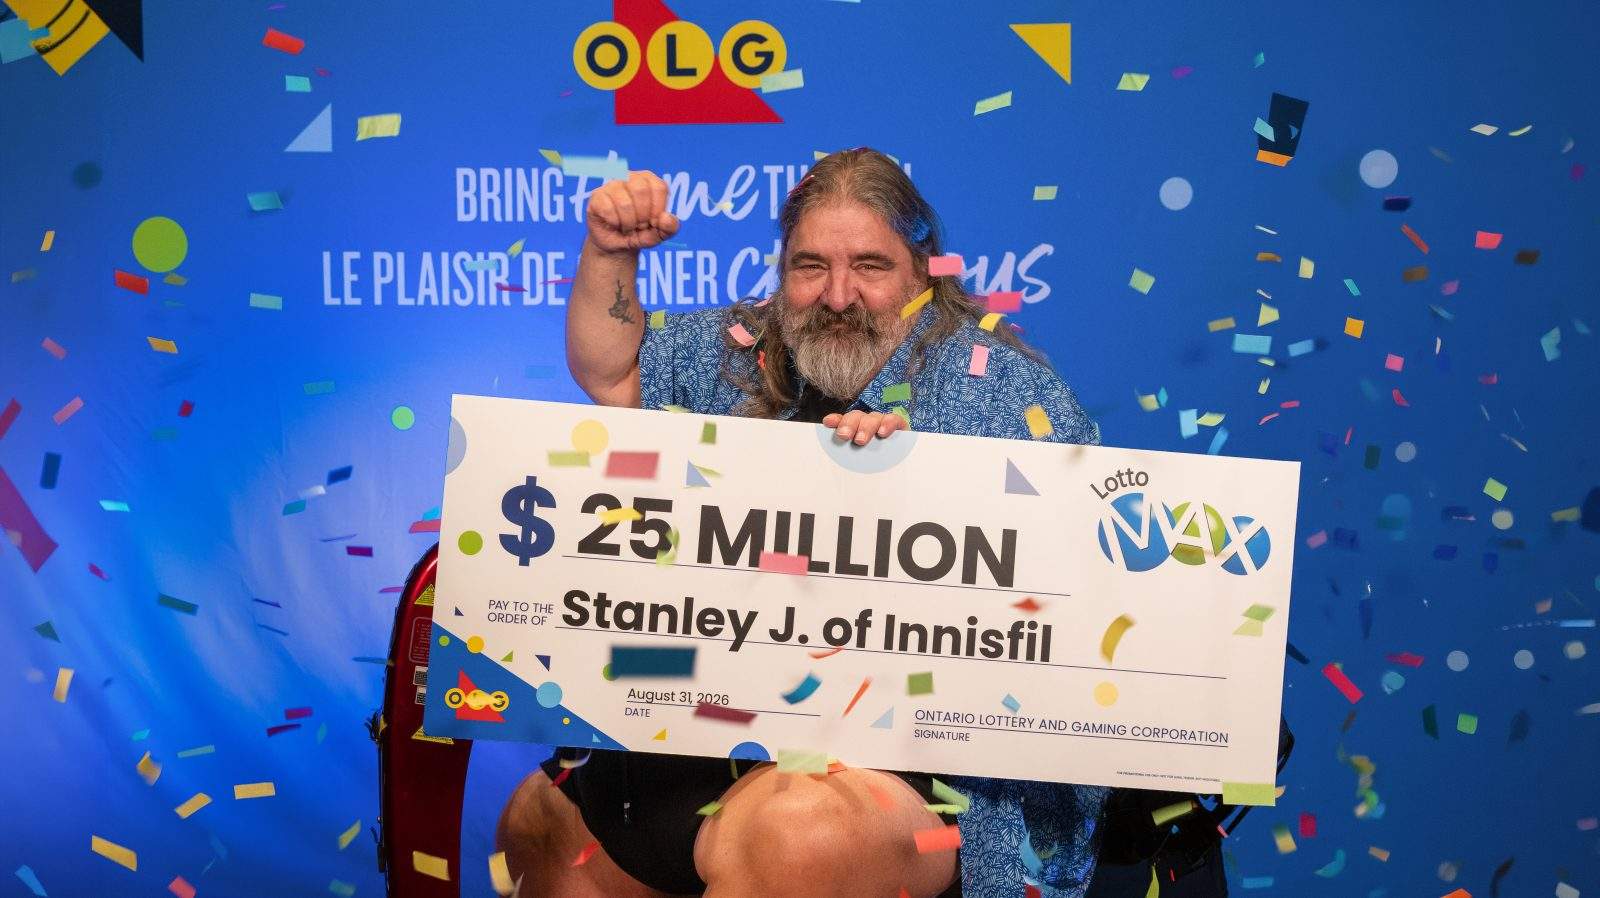
The mechanics of lottery participation represent a negative-expected-value transaction structured entirely around human cognitive bias toward low-probability, high-magnitude outcomes. When an individual purchases a state-lottery ticket, they are engaging in a voluntary taxation system characterized by a steep house edge. Yet, probabilistic models occasionally yield extreme outliers. The recent acquisition of a twenty-five-million-dollar Lotto Max jackpot by an Ontario resident provides a concrete case study for examining the financial, psychological, and systemic vectors of sudden capital acquisition.
Evaluating this event requires separating baseline probability theory from the isolated realization of an event. The structural reality of major lottery draws involves combinatorial mathematics where the odds of matching the requisite number sets are fixed at tens of millions to one. Participants trade certain capital for an infinitesimal slice of tail-risk upside. From a purely economic standpoint, the expected value of every dollar wagered is heavily discounted by administrative overhead, provincial distributions, and prize pool allocations.
Despite these fixed mathematical constraints, individual behavioral patterns dictate participation. The subject in question utilized a recurring sequence originally generated via a random terminal selection ("Quick Pick") years prior. Human heuristics often ascribe agency or persistent validity to random sequences—a cognitive phenomenon known as the illusion of control or pattern persistence. Statistically, every combination possesses an identical probability of selection in any given draw; anchoring to a static numerical string offers no mathematical advantage, yet it standardizes the consumer habit loop.
The operational transition from a wage-labor income model—in this case, decades of trade work as a plumber—to a multi-million-dollar asset holder introduces an immediate structural shock to personal finance. A twenty-five-million-dollar nominal sum does not equate to twenty-five million dollars of liquid purchasing power once tax optimization, capital preservation strategies, and asset allocation vectors are factored in (though lottery winnings in Canada are generally received tax-free as a lump sum, subsequent wealth generation is subject to standard investment taxation).
Managing this capital influx requires navigating distinct financial bottlenecks:
The Liquidity Trap occurs when sudden capital is left unoptimized in low-yield depository accounts, exposing the principal to inflationary degradation. Even at conservative inflation rates, uninvested nominal wealth loses real purchasing power rapidly.
The Asset Allocation Dilemma demands shifting from linear active income generation to non-linear portfolio yield management. Transitioning capital into tangible assets—such as real estate portfolios or fixed-income instruments—creates a defensive buffer against lifestyle creep and poor capital deployment.
The Social Friction Vector involves the rapid dissemination of windfall information within familial and social networks. As observed in this case, initial intentions to maintain privacy frequently collapse under the weight of informational diffusion, triggering demands for capital redistribution from immediate and extended networks.
The behavioral response to extreme windfalls typically follows a predictable psychological arc: acute cognitive dissonance followed by validation via tangible asset conversion. The immediate reliance on digital verification interfaces—such as lottery mobile applications—serves as the primary feedback loop for modern financial validation. Initial misreads of account balances, transitioning from modest increments to nine-figure valuations, amplify the initial shock coefficient before physical or digital ledger confirmation settles the cognitive loop.
Long-term capital preservation past an asymmetric windfall event depends entirely on institutionalizing financial guardrails. Recipients who fail to establish corporate structures, trusts, or professional wealth management advisory boards routinely experience capital depletion within a decade. The transition from physical labor markets to passive asset management requires an inversion of risk tolerance, moving the wealth holder from an operational role to a capital allocator role.
The definitive play following a low-probability, high-magnitude financial event is immediate insulation of principal through diversified, yield-generating vehicles combined with strict operational boundaries around social capital distribution. Without these structural controls, the statistical improbability of winning the capital is matched only by the probability of its eventual dissipation.