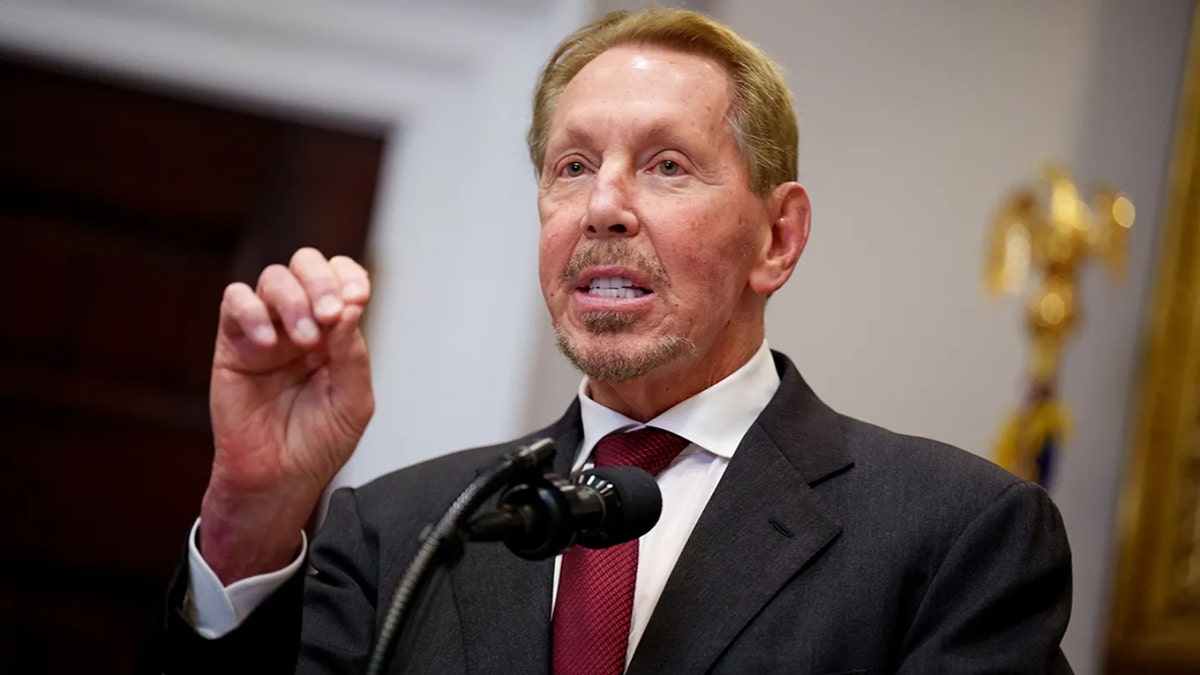
Billionaires alter their trading strategies all the time, but when Oracle co-founder Larry Ellison abruptly bins a plan to dump up to $7.5 billion worth of company shares, markets pay attention. Ellison pulled the plug on his scheduled Rule 10b5-1 trading plan barely a day after regulatory disclosures brought it to light, leaving zero shares actually sold.
If you are trying to read the tea leaves on big tech valuations, heavy infrastructure debt, and the staggering price of the artificial intelligence boom, this reversal gives you a direct window into boardroom optics. In related news, we also covered: Structural Mechanics of the Optional Practical Training Fee Proposal.
The Timing Behind the Abrupt Reversal
Ellison adopted the trading plan back in late June, targeting a window that stretched through October. At the time, Oracle shares were navigating a rocky stretch. Investors were growing visibly nervous about soaring capital expenditures. Building out data centers capable of handling massive generative workloads requires immense amounts of capital, and Oracle has been borrowing heavily and issuing stock to fund its ambitious expansion.
When a corporate insider of Ellison's stature sets up a plan to offload up to 50 million shares, markets tend to brace for impact. Even though these structured trading plans are designed to prevent accusations of insider trading, the psychological weight of a multi-billion-dollar insider exit rarely goes unnoticed. Canceling it entirely before executing a single transaction sends a strong counter-signal. It tells the market that the executive chair is keeping his skin firmly in the game while the company wrestles with its massive infrastructure pivot. The Economist has provided coverage on this critical issue in great detail.
The Real Cost of the AI Infrastructure Race
You cannot separate Ellison's stock move from the broader financial reality facing Oracle right now. The company has been racing to secure its position in the cloud and AI infrastructure race, matching wits and wallets with industry giants like Microsoft, Amazon, and Google.
That race carries a steep price tag. Oracle's capital spending has climbed dramatically, putting pressure on free cash flow and driving up debt levels as the company constructs facilities capable of hosting thousands of specialized chips. At the same time, the firm has been managing internal restructurings, including notable severance expenses and cost-management efforts to balance the books.
When companies spend aggressively on future capacity, short-term financial metrics often take a beating. Investors frequently oscillate between excitement over massive contract backlogs and panic over near-term cash burn. Ellison holding onto his massive equity stake rather than cashing out billions removes one major source of anxiety for retail and institutional holders alike.
What This Means for Shareholders Moving Forward
If you hold tech stocks or follow enterprise software closely, insider behavior acts as a useful reality check against corporate hype. Ellison remains Oracle's largest shareholder by a wide margin, and his personal fortune is deeply intertwined with the company's long-term operational success.
The decision to scrap the sale suggests confidence in the current trajectory, even as Wall Street dissects every quarterly cash flow statement and debt issuance. Skeptics will point out that corporate insiders cancel plans for personal liquidity reasons all the time, but the timing—right on the heels of earnings reports that beat headline estimates—points toward an effort to project stability.
Watch the capital expenditure numbers in upcoming quarters. The real test for Oracle isn't whether its founders hold their stock, but whether the multi-billion-dollar data center bets can translate into sustained, high-margin cloud revenue before debt servicing costs weigh down the balance sheet.