China's export boom looks unstoppable on paper, yet households back home are acting like the roof is caving in.
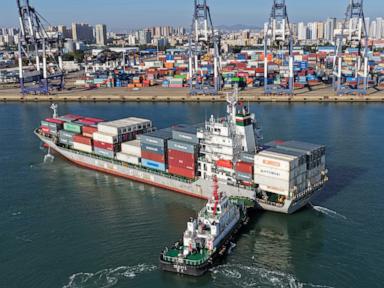
In the third quarter of 2026, gross domestic product growth accelerated to 4.5% year-on-year, picking up from a three-year low of 4.3% in the second quarter and beating analyst forecasts. By October, exports jumped 35.2% year-over-year to US$412.33 billion, pushing the cumulative trade surplus past US$1.04 trillion in just the first ten months of the year. Strip away the ships leaving ports, though, and the story flips. October retail sales of consumer goods crawled up just 0.4%, while fixed asset investment fell 8.1% over the first ten months. Learn more on a connected topic: this related article.
That split is the defining tension of China's economy right now. Beijing has kept its full-year GDP target in the 4.5% to 5% band—its lowest target since 1991—and external demand is doing the heavy lifting to keep that number alive. Still, relying on overseas buyers to carry an economy of 1.4 billion people is like flooring the gas pedal while the brakes are dragging. It gets you speed today, and creates real strain tomorrow.
What Is Actually Driving China's Export Surge
If you picture China's export engine as cheap T-shirts, plastic toys, or basic assembly lines, you're looking at last decade's map. Further journalism by Financial Times delves into similar views on the subject.
The real surge in 2026 comes from AI hardware, semiconductors, and clean-tech gear. According to data highlighted by the Information Technology and Innovation Foundation, Chinese semiconductor exports jumped 111.1% in the first ten months of 2026, while high-tech exports overall rose 47.9%. In October alone, China's high-tech manufacturing added value accelerated to 17.6% year-over-year, with industrial robots up 26%, lithium-ion batteries up 30%, and 3D printing devices up 85.9%.
Prices and global supply chains play a big role here too. Higher chip prices have inflated export values—in September, integrated circuit exports surged 136.3% by value while edging up only 1.2% by volume. Meanwhile, trade routes have shifted sharply. Exports to ASEAN countries jumped 46.3% year-over-year in October, shipments to the European Union rose 24.3%, and exports to the United States climbed 32.9% from a depressed base following tariff disputes and late-September talks between Washington and Beijing on tariff cuts across US$60 billion of trade.
Having worked closely with supply-chain planners and trade analysts over the years, one thing stands out: Chinese factories don't just win on price anymore. When a data-center builder or automakers' supplier needs rapid tooling, dense component ecosystems, or fast scaling, China's industrial clusters still move faster than almost anywhere else. Even new energy vehicle exports surged 144.7% in October as domestic carmakers pushed aggressively into foreign markets.
Why Domestic Weakness Keeps Stubbornly Holding Back Growth
So why aren't booming factories turning into booming shopping malls across China?
Because household wealth and confidence take a beating when property is still shrinking. In the first ten months of 2026, real estate development investment dropped 21.6% year-over-year, and new commercial building sales fell 14.3% to RMB 5.86 trillion. For years, real estate was the default savings vehicle for millions of Chinese families. When apartment values stall or slide and developer balance sheets stay strained, people don't suddenly go on a spending spree just because factory output rises.
Consumer numbers show that caution plainly. While the urban unemployment rate ticked down to 5.1% in October, goods consumption barely budged, rising just 0.9% across the first ten months of the year. Borrowing costs are already low, yet households and private businesses aren't rushing to take on debt. You can lower interest rates all day long, but you can't force a cautious family to buy a new car or a cautious founder to build a new plant if they feel exposed on housing, healthcare, or retirement security.
There's a nuance here that lazy headlines miss. Domestic demand isn't dead everywhere—it's rotating. Retail sales of services grew 4.9% in the first ten months of 2026, far ahead of goods at 0.9%, with online services outpacing online goods. People are spending selectively on experiences, travel, leisure, and everyday services rather than big-ticket physical goods. In the property market itself, second-hand home transactions saw an 11.4% rise in floor area traded online even as new construction slumped. That tells you buyers are hunting for value, not chasing speculative booms.
Misconceptions About This Split Economy
A common mistake outside China is assuming that strong GDP and export numbers mean the economy has "turned the corner" across the board.
- Myth: A US$1 trillion trade surplus is pure economic strength. It proves immense manufacturing scale and competitiveness. It also signals an imbalance between what Chinese factories produce and what domestic buyers absorb, while inviting tariff pushback and trade friction from major partners.
- Myth: Export gains automatically lift household spending. High-tech and capital-intensive manufacturing relies heavily on automation, specialized engineering, and global component chains. A surge in chip or battery exports doesn't automatically translate into broad wage gains or retail boom across lower-tier cities.
- Myth: The property slump is the only domestic drag. Real estate is huge, no doubt about it. Still, weak private fixed-asset investment and cautious consumer sentiment reflect deeper structural habits—high precautionary saving and uneven social safety nets—that won't vanish overnight even if housing stabilizes.
What Trade Partners, Investors, and Businesses Should Watch Next
If you track global trade, run a business tied to Asia, or manage capital exposed to China, don't wait for a neat V-shaped recovery across every sector. Look at the pressure points instead.
First, watch how trading partners respond to China's widening surplus. Surpassing US$1 trillion in ten months keeps trade negotiations, customs scrutiny, and industrial policy front and center in Brussels, Washington, and emerging markets alike. Any slowdown in global AI capital spending or new trade restrictions would hit the exact export engine propping up China's growth.
Second, separate export-facing and tech-linked winners from domestic goods plays in your own planning. If you sell consumer goods into China, expect tough competition and price sensitivity, especially in categories that leaned on subsidies. If you're active in services, healthcare, digital platforms, or supply-chain localization across Asia, demand patterns look very different from traditional real estate or brick-and-mortar retail.
Finally, test your assumptions against actual cash flows rather than headline growth rates. When an economy runs on high-tech exports alongside sluggish domestic goods demand and falling property investment, headline GDP can look calm while margins get squeezed underneath. Map your direct exposure to Chinese suppliers, buyers, and competitors now, stress-test what happens if tariffs shift or global tech orders cool, and build alternative sourcing or market options before you're forced to move in a hurry.