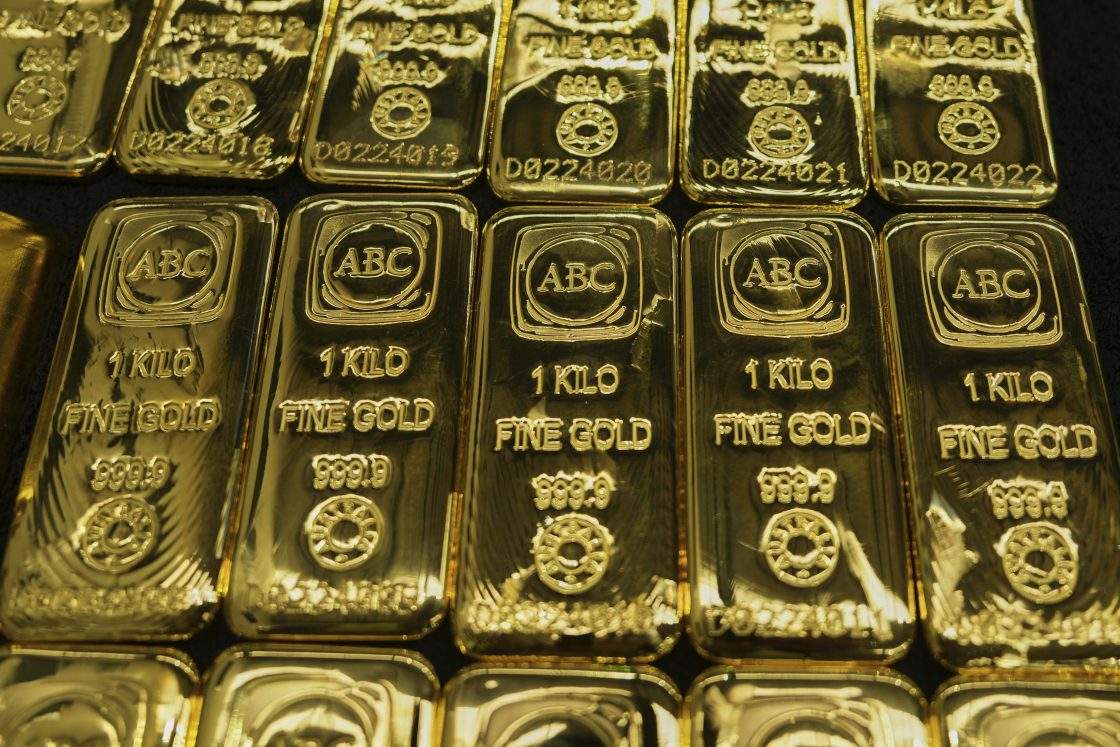
Precious metals are taking a beating. Gold and silver prices are sliding downward as soaring bond yields drain the life out of non-yielding assets, leaving investors scrambling to reallocate capital in an environment where cash actually pays a return.
When government debt offers a guaranteed four or five percent yield with zero counterparty risk, holding a shiny metal bar that pays nothing in dividends suddenly looks like an expensive hobby. That is the core mechanism driving the current sell-off in gold and silver, but the headline narrative misses the deeper structural shift happening beneath the surface. Real interest rates matter more than nominal figures, and the structural pressures on bullion go far beyond simple opportunity cost. Meanwhile, you can read similar developments here: Inside the Stelco Layoffs and the Crisis Facing Canadian Steel.
The Yield Magnet
Capital flows toward safety and return. For over a decade, zero-interest-rate policies forced money into alternative stores of value because cash was a losing proposition. Gold thrived in that vacuum.
Now, the math has flipped. As central banks kept borrowing costs elevated to combat stubborn inflation, nominal yields on sovereign bonds climbed. Institutional portfolios adjusted instantly. Why park millions in secure vaults paying zero interest when short-term Treasuries deliver predictable cash flow? To see the bigger picture, check out the excellent article by CNBC.
The opportunity cost of holding precious metals rose sharply. Every basis point increase in yields acts as an invisible tax on gold and silver ownership, squeezing speculative long positions and triggering systematic liquidations across global exchanges.
The Real Yield Equation
Nominal yields grab headlines, but real yields dictate market direction. Real yield is the nominal interest rate minus inflation expectations.
When inflation moderates while nominal rates stay high, real yields expand aggressively. That expansion is poison for precious metals. Holders of bullion face a double penalty: they receive no yield while the purchasing power of alternative fixed-income instruments matches or exceeds historical inflation hedges.
Historically, sustained periods of positive real yields coincide with prolonged consolidation phases or sharp corrections in gold prices. The market is currently relearning this hard lesson. Analysts pointing exclusively to headline inflation figures miss the mechanical reality that investors care about net purchasing power preservation, not gross inflation metrics.
Industrial Realities For Silver
Gold trades primarily as a monetary metal and a hedge against systemic risk. Silver carries a dual identity, serving as both a precious asset and an essential industrial input.
That industrial exposure changes the calculus entirely. When macroeconomic tightening cools manufacturing activity, photovoltaic production, and electronics demand, the industrial component of silver turns into a liability.
Higher borrowing costs slow down housing starts, automotive manufacturing, and tech infrastructure spending. Reduced demand from factories translates directly to soft physical consumption. While green energy transitions guarantee long-term structural demand for silver, cyclical industrial slowdowns create brutal near-term volatility that often decouples silver from gold's monetary movements.
Liquidity Drains and Margin Calls
Markets rarely move in a straight line based on fundamentals alone; leverage amplifies every turn.
When bond yields spike, financial institutions face margin pressures across broader asset classes. Liquidity becomes scarce. To cover losses or meet collateral requirements elsewhere in their portfolios, large funds often sell what is liquid, not what they want to part with.
Precious metals markets provide deep liquidity. During sudden liquidity squeezes, traders routinely dump profitable or stable gold and silver holdings simply to raise cash. This forced deleveraging accelerates price drops independently of long-term economic arguments for holding bullion.
The Structural Paradox
Despite the current downward pressure, sovereign debt levels across major economies continue to spiral upward at an unsustainable pace. National deficits are expanding, not shrinking, regardless of political rhetoric.
This creates a fascinating paradox for long-term observers. Central banks are maintaining high interest rates to fight inflation today, while simultaneously backing a global financial system saddled with debt loads that make those very interest rates increasingly unaffordable over the long haul. At some point, the cost of servicing sovereign debt forces monetary authorities to blink.
When central banks eventually pivot back toward accommodation, real yields will compress again, and the institutional capital currently parked in short-term bonds will search desperately for hard assets. Until that inflection point arrives, gold and silver must navigate a punishing environment defined by high yields, strong currency valuations, and aggressive quantitative tightening.